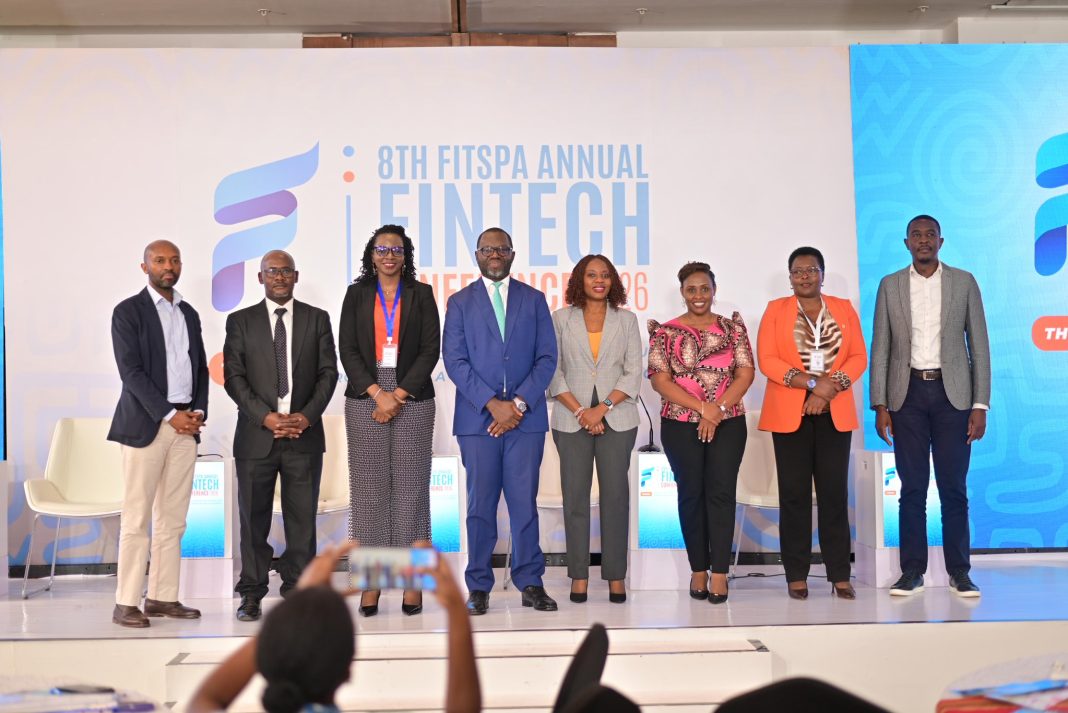
Uganda’s fintech sector has asked the government to establish a dedicated fintech fund to finance local innovation, build technical capacity and help homegrown technology companies develop solutions capable of supporting the country’s digital economy and the 10X Growth Strategy.
The proposal was one of the key demands raised during the eighth FITSPA Annual Fintech Conference held at the Sheraton Kampala Hotel on October 6 and 7, bringing together fintech companies, financial institutions, regulators, investors, technology providers, development partners and policymakers.
The conference was held under the theme, “Scaling Fintech Innovation for Inclusive Growth and a Resilient Digital Economy,” with more than 700 delegates, 50 panelists and 30 exhibitors expected to participate in discussions on the future of digital finance in Uganda.
Participants argued that while Uganda has developed a growing fintech ecosystem, many local companies still face difficulties accessing capital, technology, devices, skills and infrastructure needed to move from promising ideas to businesses capable of operating at scale.
They called for the government to work with the private sector and development partners to create a fintech fund that would provide financing for locally developed projects, strengthen technical capacity and support solutions that can contribute to financial inclusion and productivity.
The sector also asked the government to consider targeted tax relief on smartphones and merchant payment services to make digital financial services more affordable and accessible to ordinary Ugandans and small businesses.
Participants further called for incentives to attract foreign investors into Uganda’s fintech industry, arguing that increased investment would bring capital, expertise, technology and access to international markets.
One of the participants said the proposed fund should not merely finance individual startups but should help create the infrastructure and capacity required for Uganda to develop its own globally competitive fintech industry.
“The people in the room have agreed through the association that there is a need to start up a fintech fund. And this is to support building the local capacity,”the participant said.
The call comes at a time when government is seeking to use digital transformation as one of the pillars of its Tenfold Growth Strategy, with Finance Minister Henry Musasizi repeatedly urging the financial sector to develop products that finance productive economic activity and expand meaningful financial inclusion.
Presenting Musasizi’s message, Assistant Commissioner Bob Bonabo Munene of the Ministry of Finance, Planning and Economic Development challenged fintech companies to look beyond transactions and position themselves as engines of production, investment, savings, enterprise growth and wealth creation.
Munene said fintech companies must also take digital financial services to people who remain underserved, including farmers, small traders, women running household enterprises, young entrepreneurs and businesses operating in border communities.
He said the industry should use transaction data responsibly to help small businesses build financial identities and qualify for appropriate financing, while warning against an approach that simply increases the number of digital loans without creating productive economic activity.
“Uganda needs productive digital credit, not simply more digital loans,” Munene said.
The message is consistent with Musasizi’s wider position that Uganda’s financial sector must expand long-term and affordable financing for productive sectors as the country works towards a US$500 billion economy by 2040. The minister has also identified digital finance and fintech among areas requiring greater attention as Uganda pursues its economic transformation agenda.
The fintech sector’s demand for a dedicated fund also comes as companies continue to highlight the challenge of raising capital and reaching customers with the devices required to participate in the digital economy.
At the conference, Mina Shahid, founder and chief executive officer of Numida, argued that capital alone would not be enough to drive enterprise growth, pointing to the importance of data, technology, innovation, intellectual capital and access to devices.
The Numida discussion also highlighted the potential of transaction data, interoperability and application programming interfaces to create stronger credit histories and enable financial products tailored to the needs of underserved businesses.
The issue of device affordability received further attention through a partnership involving the United Nations Capital Development Fund and Rich Black under the 10X Programme, with support from the Mastercard Foundation.
Shakila Kerre, a senior development professional and MSME and fintech financing specialist at UNCDF, said the partnership would test device financing for young micro, small and nano enterprises seeking smartphones, tablets and laptops for productive use.
“The focus is on helping young MSMEs access smartphones, tablets and laptops for productive use. We are bringing a new concept to the market: device financing for active use,” Kerre said.
Rich Black Communications Director Harriet Asiimwe separately told participants that fintech companies could partner with device financing providers to reach rural households, smallholder farmers, women entrepreneurs, young people, savings groups, SACCOs and agricultural cooperatives.
She said such partnerships could allow customers to pay an initial 20 percent of the cost of devices and clear the balance over time, making smartphones and other digital tools more accessible to people who cannot afford to buy them outright.
The conference also placed strong emphasis on interoperability, with industry players arguing that fragmented payment systems continue to make it expensive and complicated for businesses to scale across Uganda and other African markets.
Jessica Tusime, country director of pawaPay Uganda, said her company’s experience operating across 43 markets and connecting to 42 mobile money operators demonstrates the difficulties businesses face when they have to establish multiple integrations whenever they enter a new market.
She said Uganda can build successful fintech companies, but the systems should be designed in a way that allows them to expand into other African markets without starting the integration process from scratch.
A separate panel involving MTN MoMo, pawaPay and local fintech players called for stronger partnerships, standardised rules for recurring payments and direct debit, and more resilient payment infrastructure to support the growth of Uganda’s subscription economy, cross-border payments and e-commerce.
The conference also showcased how established Ugandan fintech companies have evolved alongside the country’s digital payments industry.
Yo Uganda, which marked 20 years in the digital payments space, used the conference to highlight its journey from providing SMS, USSD and IVR services to offering payment gateways, application programming interface integrations, collections, international remittances and bank integrations.
Lawrence Totimeh, the company’s head of business and service delivery, said Yo’s technology rails now support payments and collections for businesses, government agencies, not-for-profit organisations and other institutions.
The growth of digital payments was also reflected in MTN MoMo’s participation. The company said its Day Two discussions focused on how fintech companies, banks and technology businesses can collaborate, connect their systems and use artificial intelligence to build the next generation of digital businesses.
Meanwhile, Yellow Card used the conference to promote stablecoins as a potential tool for improving cross-border payments. Isaac Wabuge of Yellow Card said the company had processed US$10 billion, operates in more than 20 countries and has more than 35 live payment corridors.
He said stablecoin-based settlement could reduce the time required for cross-border transactions from several days to seconds, while providing banks, fintechs and mobile money operators with access to payment rails, wallets and compliant dollar liquidity through a single integration.
The conference also highlighted the need for responsible digital lending as fintech companies expand access to credit.
FITSPA and UNCDF recognised digital lenders that have subscribed to the Code of Conduct for Responsible Digital Lending, including Furaha Financial, Zenka Finance, Fido, Unifi, M-KOPA, Flow Global, JUMO and Numida.
The code promotes transparency, responsible lending, data protection, fair debt collection and effective complaints handling, with the organisers urging digital lenders to incorporate the principles into their governance, product development and credit assessment processes.
Furaha Financial, which participated in discussions on responsible digital credit, said the sector must ensure that digital borrowing becomes a tool for productive finance rather than simply making it easier for consumers to take loans. The company joined a panel involving CGAP, UNCDF, gnuGrid Credit Reference Bureau and Pearl Bank to discuss the future of responsible digital credit.
For Uganda’s fintech industry, the two-day conference therefore ended with a common message: innovation must now translate into scale, investment, productive finance and wider economic participation.
The proposed fintech fund is being positioned as one of the mechanisms that could help bridge the gap between innovation and scale by providing local companies with the capital and technical support needed to build solutions for Uganda and eventually compete across Africa.
As the conference closed, Munene urged the private sector to match Uganda’s economic ambitions by moving beyond financial transactions and helping citizens save, invest, build businesses and create wealth.
“Fintech must match innovation with the scale of Uganda’s economic ambitions,” Munene said.
The challenge now lies with government, regulators, investors and industry players to turn the proposals raised at the eighth FITSPA conference into practical interventions that can make digital finance cheaper, safer and more accessible while giving Ugandan fintech companies the opportunity to grow into regional and global businesses.